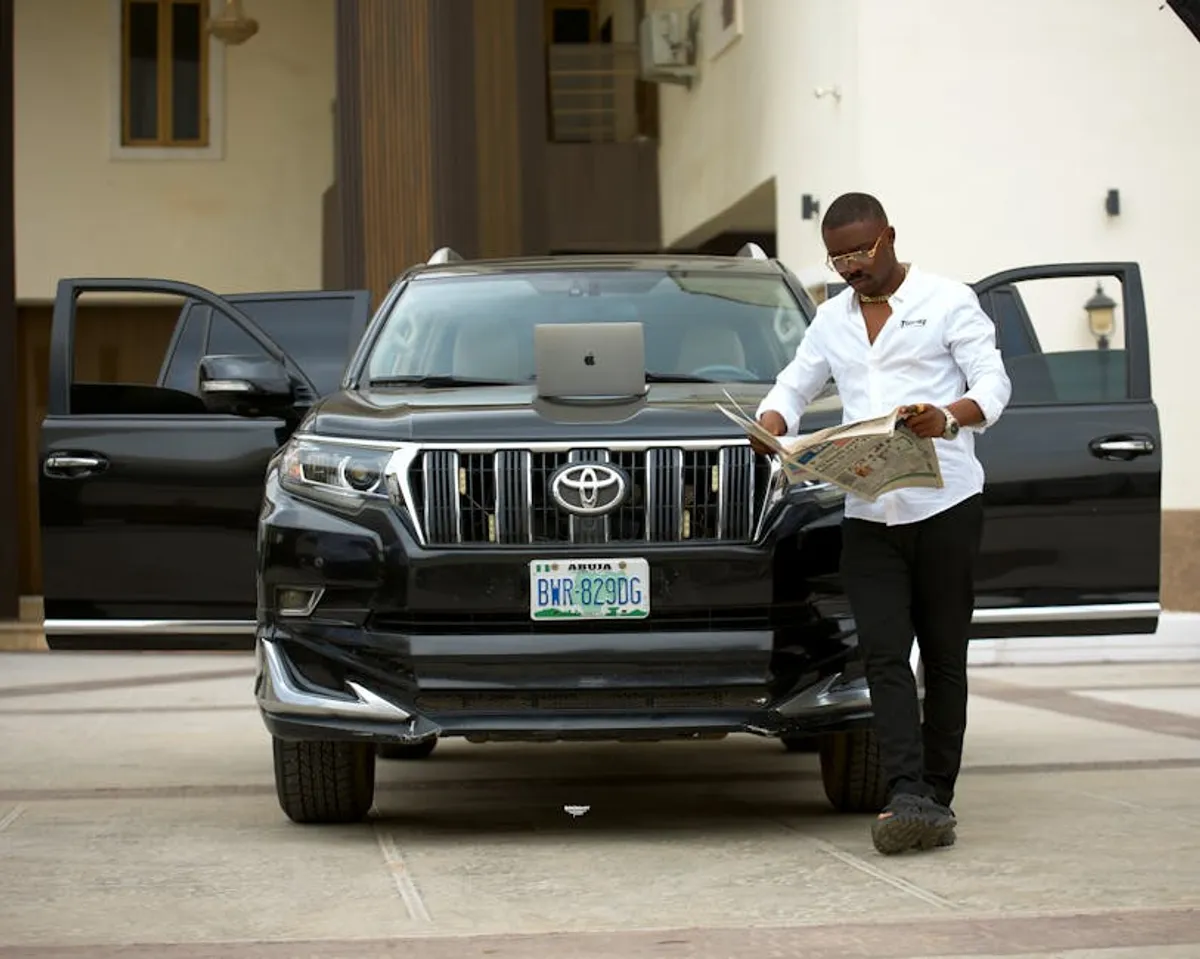
Understanding the insurance implications for a used SUV is a critical component of the overall purchase decision, often overlooked until after the sale. While a used SUV typically presents a more budget-friendly entry point than a new model, the cost savings on the vehicle itself do not automatically translate to lower insurance premiums. Multiple variables, ranging from the specific make and model's safety ratings and repair costs to your personal driving history and chosen coverage levels, directly influence how much you will pay. Drivers need to evaluate these factors proactively to avoid unexpected expenses and ensure adequate financial protection.
Key Vehicle Attributes Impacting Used SUV Insurance Premiums
The characteristics of the used SUV itself play a significant role in determining its insurance cost. Insurers assess risk based on how likely a particular vehicle is to be involved in an accident, stolen, or require expensive repairs.
Vehicle Make, Model, and Year
Newer vehicles generally cost more to insure due to their higher replacement value. However, for used SUVs, the depreciation curve can work in your favor. An older model, while having a lower market value, might still command higher premiums if its parts are scarce or expensive, or if it has a history of high repair costs. Conversely, a popular model with readily available parts might be cheaper to insure even if it's slightly newer.
- Depreciation: As vehicles age, their market value decreases, potentially lowering the cost of collision and comprehensive coverage which are tied to the vehicle's actual cash value.
- Repair Costs: SUVs with complex technology, specialized components, or luxury branding often have higher repair costs, which directly translates to increased insurance premiums. For example, a used luxury SUV might cost more to insure than a used mainstream SUV of the same year due to parts and labor expenses.
- Parts Availability: Vehicles with common parts that are easy to source and replace tend to have lower repair-related insurance costs.
Safety Features and Ratings
Modern safety features can significantly reduce insurance premiums. Insurers favor vehicles equipped with advanced driver-assistance systems (ADAS) like automatic emergency braking, lane-keeping assist, and blind-spot monitoring because they demonstrably lower the likelihood of accidents. Even for used SUVs, look for models that scored well in crash tests from organizations like the Insurance Institute for Highway Safety (IIHS) and the National Highway Traffic Safety Administration (NHTSA). A "Top Safety Pick+" rating, for instance, often indicates a lower risk profile for insurers.
Engine Size, Performance, and Theft Rates
SUVs with larger, more powerful engines are often associated with higher speeds and, consequently, a greater risk of accidents. This can lead to increased premiums. Additionally, certain SUV models are statistically more prone to theft than others. Insurers track these trends, and if your chosen used SUV model appears frequently on "most stolen" lists, your comprehensive coverage costs will likely reflect that elevated risk.
Personal Factors Influencing Your Premium
Beyond the vehicle itself, your individual circumstances and choices are major determinants of your used SUV's insurance cost.
Driving Record and Experience
A clean driving record—free of accidents, speeding tickets, or other moving violations—is the single most impactful factor in securing lower insurance rates. Insurers view drivers with a history of responsible driving as lower risk. Conversely, a record with recent incidents will lead to higher premiums, regardless of the vehicle type.
Location and Demographics
Where you live and where your SUV is parked can significantly alter your insurance rate. Urban areas with higher traffic density, greater rates of theft, or increased vandalism claims typically result in higher premiums than rural or suburban locations. Your age and, in some regions, your credit score can also influence rates, with younger, less experienced drivers and those with lower credit scores often facing higher costs.
Coverage Choices and Deductibles
The type and amount of coverage you select directly impact your premium. Opting for minimum state-mandated liability coverage will be cheaper than comprehensive coverage. However, skimping on coverage for a valuable used SUV can leave you financially exposed. Choosing a higher deductible (the amount you pay out-of-pocket before insurance kicks in) will lower your premium, but requires you to have more cash readily available in case of a claim.
Pro Tip: When considering an older used SUV, carefully weigh the cost of full coverage (collision and comprehensive) against the vehicle's actual cash value. If the annual premium for full coverage approaches or exceeds a significant percentage of the SUV's market value, it might be more financially prudent to opt for liability-only coverage, provided you can absorb the cost of repair or replacement out-of-pocket.
Strategies for Reducing Used SUV Insurance Expenses
Even with a specific used SUV in mind, several actionable steps can help mitigate insurance costs.
Compare Quotes: This is the most crucial step. Insurance rates vary widely between providers for the exact same coverage. Obtain quotes from at least three to five different insurers before committing. Online comparison tools can streamline this process.
Bundle Policies: Many insurers offer discounts for bundling multiple policies, such as combining your auto insurance with homeowners or renters insurance. This can often result in significant savings across all policies.
Increase Deductibles: As mentioned, a higher deductible reduces your premium. Ensure you can comfortably afford the deductible amount in an emergency.
Maintain a Clean Driving Record: Avoid traffic violations and accidents. Many insurers offer "good driver" discounts for extended periods without claims or infractions.
Inquire About Discounts: Always ask about available discounts. Common ones include multi-car discounts, good student discounts (for younger drivers), low-mileage discounts, anti-theft device discounts, and discounts for taking defensive driving courses.
Choose Wisely: Before purchasing, research the insurance costs associated with specific used SUV models you are considering. Some models are inherently cheaper to insure due to their safety records, repair costs, and theft statistics.
Navigating Your Used SUV Insurance Decision
Securing insurance for a used SUV requires a nuanced approach, balancing cost with adequate protection. The initial sticker price of a used SUV is only one part of the financial picture. Proactively researching insurance implications based on the vehicle's characteristics and your personal profile allows for a more informed purchase. By comparing quotes, leveraging available discounts, and making strategic choices about coverage levels and deductibles, drivers can effectively manage their overall ownership costs and ensure peace of mind on the road.
Frequently Asked Questions
Is insurance for a used SUV always cheaper than a new one?
Not always. While the lower replacement value of a used SUV can reduce collision and comprehensive premiums, factors like the specific model's repair costs, parts availability, theft rates, and your personal driving history can still make insurance expensive. In some cases, a new SUV with advanced safety features might even be cheaper to insure than an older, less safe used model.
Does the age of an SUV affect insurance costs?
Yes, generally. Older SUVs typically have lower market values, which can lead to reduced collision and comprehensive coverage costs. However, very old or classic SUVs might see increased premiums if parts are rare or specialized mechanics are required for repairs.
What makes some used SUVs more expensive to insure than others?
High-performance engines, poor safety ratings, a history of frequent theft, expensive replacement parts, and a reputation for high repair costs are all factors that can increase insurance premiums for specific used SUV models.
Should I get full coverage on an older used SUV?
The decision for full coverage (collision and comprehensive) on an older used SUV depends on its actual cash value and your financial situation. If the SUV's market value is low, the annual cost of full coverage might not be worth it, especially if you can afford to repair or replace the vehicle yourself. Always compare the premium cost to the vehicle's value to make an informed choice.