The used-EV depreciation curves over the past eighteen months have moved in a direction that is producing some real conversations inside the leasing companies and the captive finance arms, conversations that have not yet shown up in the consumer-facing commentary about EV ownership economics. The wholesale numbers on three-year-old EVs are substantially weaker than the residual-value assumptions that supported the lease pricing those vehicles were sold under, and the implications are starting to work through the system in ways that consumers, dealers, and the OEMs themselves are going to have to navigate over the next several quarters.
This is not an "EVs are bad" story. The technology continues to develop, the new-vehicle market is producing better products at improving prices, and the long-term trajectory of EV adoption remains broadly intact. But the secondary market for the EVs that were sold in 2021, 2022, and 2023 is working through a depreciation cycle that nobody in the industry was modeling at the time those vehicles were originally financed, and pretending the situation is not real does not help anyone navigate it.
What the wholesale numbers actually show
The Manheim and Black Book wholesale data for three-year-old EVs across most non-premium segments shows depreciation curves that are running substantially steeper than comparable ICE vehicles in the same model years. The specific numbers vary by segment and by manufacturer, but the general pattern is consistent — wholesale values at 36 months are running 15 to 30 percentage points below where comparable ICE wholesale values would be tracking, with some specific models showing even larger gaps.
The drivers are partly technology-related and partly market-related. The battery technology improvements over the past three years mean that a 2022 EV has measurably less range and slower charging than a comparably-priced 2025 EV, and that real product difference shows up in wholesale demand. The market dynamics are partly about EV demand softening at the consumer level over the past eighteen months, which reduces the pool of used-EV buyers and pushes wholesale values lower at the margin where they actually clear.
There is also a financing dynamic. The new-vehicle EV pricing has been adjusted aggressively over the past two years as manufacturers have worked through inventory and as competition has intensified. The price cuts on new vehicles flow through to used-vehicle valuations almost mechanically — a used vehicle cannot be worth more than what a new equivalent costs minus a reasonable depreciation discount, and the new-vehicle price reductions have pulled the used-vehicle ceilings down with them.
The leasing-company exposure
The implications for the leasing companies are substantial. The leases that were written in 2021 and 2022 priced residual values at levels that assumed normal EV depreciation behavior, which at the time was an open question because there was not enough historical EV lease data to calibrate the residual-value models with high confidence. The assumed residuals were generally in the range of 50 to 60 percent of MSRP at 36 months for the volume EV segment, which was broadly comparable to ICE residual assumptions for similar vehicle classes.
The actual wholesale values that those vehicles are now showing at lease end are running materially below the assumed residuals. The captive finance arms, which absorb the residual-value risk on most leases written through OEM-affiliated financing, are taking the financial impact of the gap between assumed and actual residual values.
"The numbers we're seeing on the off-lease EVs are not what was modeled," one captive finance executive told me, asking not to be named because the company's public commentary on residual performance is managed through the corporate communications function. "The volume is significant enough that you can see it in the financial reporting if you know what to look for, but the bigger question is what we assume for the leases we're writing now."
What this means for new EV lease pricing
The lease pricing on current new EVs has been adjusted to reflect the more cautious residual assumptions that the recent experience supports. Lease offers on new EVs are generally less aggressive than they were two years ago in residual-value terms, with monthly payments calibrated for residuals that assume continued elevated depreciation rather than a return to the pre-2023 assumptions.
The implications for consumer EV economics are real. The lease offers that made EVs financially attractive on a monthly-payment basis in 2022 and early 2023 were partly supported by residual assumptions that did not hold up. The current lease offers reflect more realistic residual assumptions, which means the monthly payments are higher relative to the vehicle MSRP than they were during the peak-incentive period.
The OEMs that have been working to maintain EV sales volumes have generally responded by either lowering MSRP directly or by providing more aggressive cash incentives that effectively reduce the cap cost on which the lease is calculated. These approaches address the consumer affordability question without putting more pressure on the residual-value assumptions, which is the financial position the captive finance arms can sustain.
The off-lease pipeline that is about to hit the market
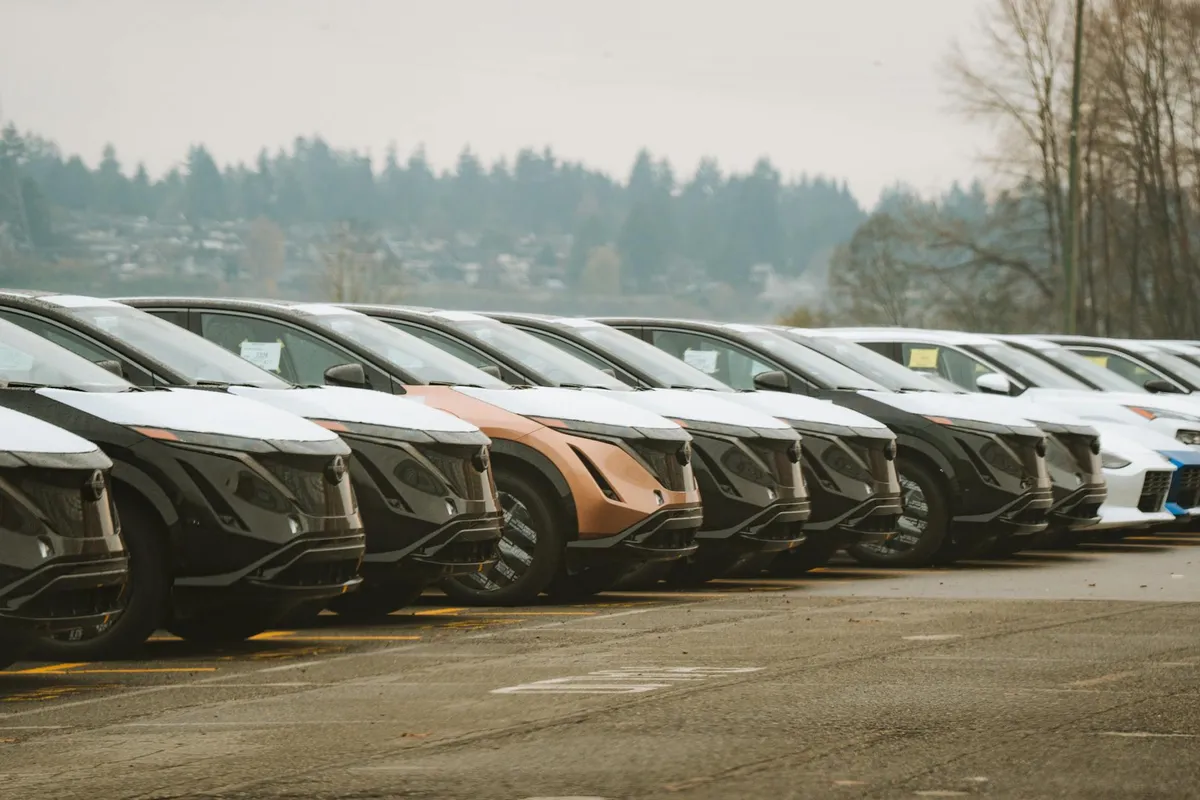
The off-lease EV volumes are about to step up substantially. The 2022 and 2023 EV lease cohorts were larger than the 2020 and 2021 cohorts because EV new-vehicle sales were ramping during those years, and the returns from those leases are about to come back through the wholesale channel in volumes that the used-EV market has not seen before.
The supply increase will probably keep wholesale prices under pressure for at least the next several quarters. The demand pool for used EVs — buyers who are willing to take on the older battery technology, the slower charging, and the more limited range relative to current new vehicles — is real but limited. The price discovery that is happening at the wholesale level is finding the demand at lower prices than the residual-value models assumed.
The consumer-side implications are mixed. For consumers who are willing to buy a used EV, the price environment is favorable — there are good used EVs available at prices that represent substantial discounts to comparable new vehicles. For consumers who are coming off EV leases and considering buying out the vehicle, the math has generally moved in favor of buying the vehicle at the residual price rather than returning it and buying a different vehicle, because the residual price specified in the lease is generally below current market value of the same vehicle.
What the dealers are seeing
The dealer-side perspective on the used-EV market has shifted noticeably over the past eighteen months. Dealers who two years ago were actively trying to stock used EVs as the technology became more mainstream are now more selective about which EVs they will take in trade and at what prices. The auction-floor commentary suggests that wholesale demand from dealers for off-lease EVs has been more concentrated in specific segments and specific brands, with weaker generalized demand than the EV-adoption narrative would suggest.
The captive finance arms have responded in part by working with their dealer networks to absorb off-lease vehicles into certified pre-owned programs at the dealer level rather than letting the vehicles flow to wholesale auction. The CPO approach maintains some control over the price discovery and provides a marketing pathway for the vehicles that wholesale auction would not provide. But the volumes being absorbed through CPO are limited by what the dealer network can actually move, and the residual flows through to wholesale where the pricing pressure is most visible.
Why this matters beyond the leasing companies
The used-EV depreciation pattern has implications beyond the leasing companies and the OEMs themselves. The total cost of ownership comparison that EV advocates have used to argue for EV adoption depends substantially on what the vehicle is worth at the point of resale, and the current depreciation pattern shifts that math meaningfully relative to what was assumed two and three years ago.
The consumer financing of new EVs is also affected. Auto loans for new EVs increasingly need to be structured with longer terms or smaller loan amounts to keep monthly payments at affordable levels, and the longer-term loans on assets that are depreciating faster than historical patterns create negative-equity situations that constrain the consumer's ability to trade out of the vehicle later in the loan term.
The new-vehicle pricing for EVs continues to be adjusted to manage these dynamics. The price reductions that have been pushed through over the past two years are partly a response to the demand environment but partly also an acknowledgment that the financing economics that supported the higher MSRP levels no longer hold. The new MSRP levels reflect a more realistic assessment of what consumers will pay given the depreciation patterns the secondary market is establishing.
The depreciation cycle will probably normalize at some point as the technology stops improving as rapidly and as the new-vehicle pricing stabilizes. But the next several years are going to involve continued adjustment in how EVs are priced, financed, and valued, and the consumers and dealers who navigate that period successfully are going to need to understand what the wholesale numbers are actually doing rather than what the marketing materials suggest.