Insuring a Toyota Tundra involves navigating a range of variables that directly impact premium costs. As a full-size pickup, the Tundra presents a distinct insurance profile compared to smaller vehicles or sedans. Drivers evaluating a Tundra purchase, or current owners seeking to optimize their coverage, must understand the specific factors insurers weigh. These include the truck's inherent characteristics, the driver's personal history, and the chosen policy structure. The goal is to secure adequate protection without overpaying, requiring a detailed look at how these elements converge to determine your annual or monthly insurance expenditure.
Key Factors Influencing Toyota Tundra Insurance Premiums
Insurance premiums for any vehicle, including the Toyota Tundra, are not uniform. They are the result of an actuarial assessment of risk, which considers both the insured asset (the truck) and the insured party (the driver).
Vehicle Specifications and Trim Levels
The specific configuration of your Toyota Tundra plays a significant role in its insurance cost. Newer models, particularly those with advanced driver-assistance systems (ADAS) and complex electronics, often incur higher comprehensive and collision premiums. This is due to the increased cost of repairing or replacing sophisticated sensors, cameras, and computer modules following an incident. For instance, a Tundra Capstone with its premium interior and technology suite will likely cost more to insure than a base SR model, as its repair parts are more expensive and specialized. Engine size also matters; a larger engine can imply higher performance and, statistically, a greater potential for high-speed incidents, though this effect is often less pronounced for trucks than for sports cars. The Tundra's strong safety ratings, however, can partially offset these costs, as vehicles with lower injury claims tend to receive more favorable rates.
Driver Profile and History
Your personal driving record is a primary determinant of insurance costs. A history free of accidents and moving violations signals lower risk to insurers, leading to more competitive rates. Conversely, past claims, speeding tickets, or DUI convictions will significantly elevate premiums due to the increased likelihood of future incidents. Age is another critical factor; younger drivers (under 25) typically face higher rates because statistical data shows they are more prone to accidents. Geographic location also impacts costs, as urban areas with higher traffic density, theft rates, and vandalism statistics generally result in pricier insurance than rural regions. Finally, your credit score, in many states, can influence premiums, with higher scores often correlating with lower insurance costs, as insurers view it as an indicator of financial responsibility.
Coverage Types and Deductibles
The specific coverages you select and the deductibles you choose directly shape your premium. A basic liability-only policy, which covers damage to other vehicles and property, will be the least expensive but offers no protection for your own Tundra. Adding collision coverage (for damage to your truck in an accident) and comprehensive coverage (for non-collision events like theft, vandalism, or natural disasters) will increase your premium, as these protect your asset. Uninsured/underinsured motorist coverage and medical payments coverage also add to the cost but provide crucial protection. Your deductible — the amount you pay out-of-pocket before insurance kicks in for collision and comprehensive claims — also matters. Opting for a higher deductible (e.g., $1,000 instead of $500) will lower your premium, as you are assuming more of the initial financial risk. This trade-off requires careful consideration of your financial comfort level.
Average Toyota Tundra Insurance Costs by Model Year
The model year of your Toyota Tundra influences insurance costs primarily through its depreciation, repair complexity, and theft risk. Newer Tundras typically command higher comprehensive and collision premiums due to their higher market value and the often-costly advanced technology components. For instance, a 2023 Tundra with its hybrid powertrain options and advanced infotainment system will likely have higher repair costs for specific components compared to a 2015 model. As a Tundra ages, its market value decreases, often leading to lower comprehensive and collision premiums because the potential payout for a total loss is reduced. However, liability coverage, which covers damage to other parties, remains relatively stable across model years, as it's less tied to the value of your own vehicle. Theft rates can also fluctuate by model year, with some generations being more targeted than others, which can impact comprehensive premiums. Regional variations and specific insurer algorithms mean these averages are broad estimates, and personalized quotes are essential. For instance, a 2023 Tundra with its hybrid powertrain options and advanced infotainment system will likely have higher repair costs for specific components compared to a 2015 model, so understanding the 2023 Tundra's reliability is key.
Pro Tip: When considering vehicle modifications, particularly those that enhance performance or alter the truck's original specifications, inform your insurer in advance. Many modifications can increase your premium due to higher repair costs or altered risk profiles, and failing to disclose them could lead to claim denials.
Strategies to Reduce Your Toyota Tundra Insurance Costs
While some factors influencing Tundra insurance are fixed, several actionable strategies can help mitigate your premium expenses without compromising essential coverage.
Bundling Policies
Many insurance providers offer discounts for bundling multiple policies, such as combining your auto insurance with homeowners, renters, or even life insurance. This can result in savings of 5% to 25% on your total premiums, as insurers reward customers who consolidate their business with them.
Vehicle Safety Features and Anti-Theft Devices
The Toyota Tundra comes equipped with various standard safety features, such as stability control, anti-lock brakes, and multiple airbags. Ensure your insurer is aware of these. Additionally, installing aftermarket anti-theft devices, such as car alarms, tracking systems, or immobilizers, can qualify you for further discounts, as these reduce the risk of vehicle theft.
Maintaining a Clean Driving Record
The most direct way to control your insurance costs over time is to drive safely. Avoiding accidents and traffic violations, especially major ones like DUIs, will keep your premiums lower. Many insurers offer "good driver" discounts after a certain period (e.g., 3-5 years) without claims or infractions.
Adjusting Deductibles and Coverage Limits
Increasing your collision and comprehensive deductibles can significantly lower your premiums. For example, moving from a $500 to a $1,000 deductible might reduce your premium by 10-20%. This strategy is most effective if you have sufficient emergency savings to cover the higher out-of-pocket expense should a claim arise. For older Tundras with lower market value, you might also consider reducing or dropping collision and comprehensive coverage entirely if the annual premium cost approaches a significant percentage of the truck's actual cash value.
Shopping Around and Comparing Quotes
Insurance rates vary widely between providers, even for the same driver and vehicle. It is crucial to obtain quotes from multiple insurers annually or whenever your policy is up for renewal. Online comparison tools and independent agents can help streamline this process, allowing you to identify the most competitive rates for your specific Tundra and coverage needs.
- Inquire about usage-based insurance programs if you drive less frequently.
- Ask about discounts for defensive driving courses.
- Explore discounts for paying your premium in full annually rather than monthly.
- Consider a multi-car discount if you insure more than one vehicle with the same company.
Understanding How Insurers Rate the Tundra
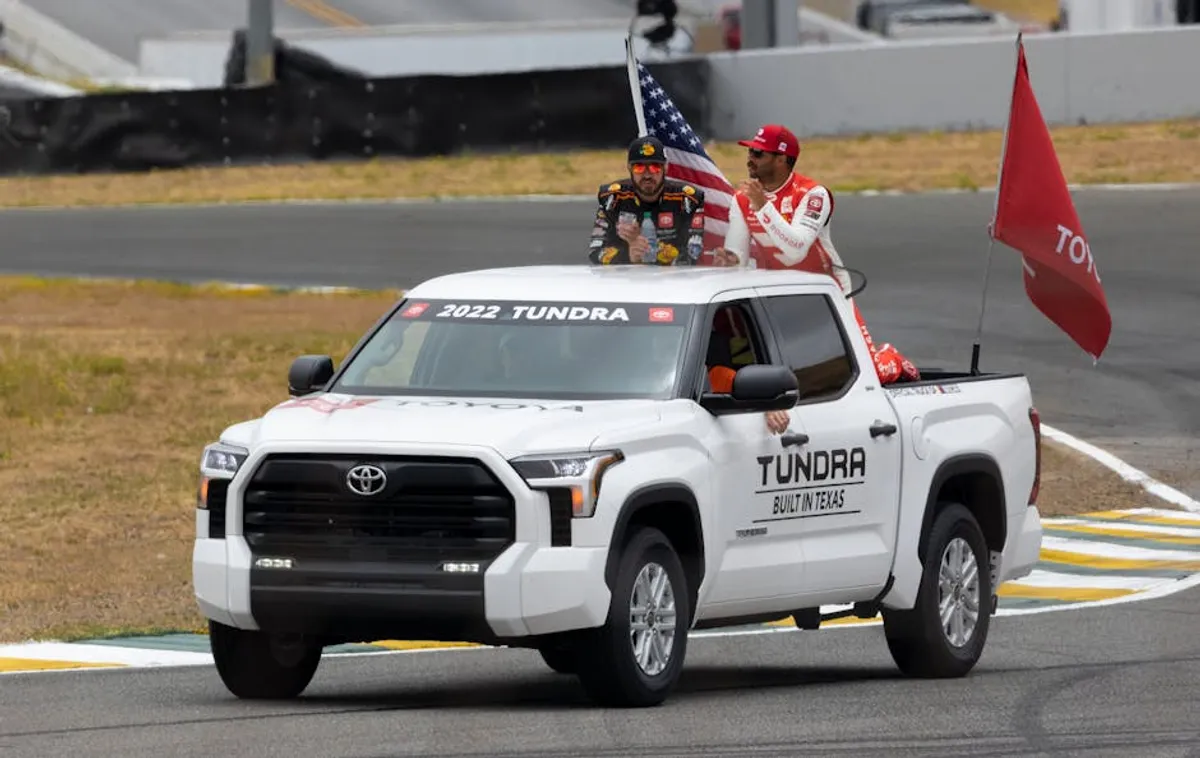
Insurers classify the Toyota Tundra as a full-size pickup truck, which influences its rating in several ways. Full-size trucks often have higher liability limits due to their potential for causing more significant damage in an accident compared to smaller passenger cars. The Tundra's robust construction and higher ride height can contribute to lower injury rates for its occupants, which can positively influence personal injury protection (PIP) and medical payments coverage costs. However, the cost of parts and labor for truck-specific components, like bed repairs or heavy-duty suspension, can be higher than for conventional sedans, impacting collision and comprehensive premiums. The Tundra's reputation for reliability and resale value can also be a subtle factor, as vehicles that hold their value well may be perceived as less risky for total loss claims over time. Theft rates for specific truck models are also continuously monitored, and if a particular Tundra generation becomes a target, comprehensive premiums can adjust accordingly.
Navigating Your Toyota Tundra Insurance Options
Securing the right insurance for your Toyota Tundra is a continuous process, not a one-time decision. Your driving habits, the truck's age, and market conditions all evolve, necessitating periodic review of your policy. Start by accurately assessing your coverage needs, considering your financial situation and the value of your Tundra. Prioritize essential coverages like liability, and then layer on collision and comprehensive as appropriate for your vehicle's value. Proactively seek out discounts, maintain a clean driving record, and make it a habit to compare quotes from multiple providers at least once a year. This diligent approach ensures you maintain adequate protection for your investment while managing costs effectively.
Frequently Asked Questions
Is Toyota Tundra insurance expensive compared to other trucks?
Toyota Tundra insurance costs are generally comparable to other full-size pickup trucks in its class, such as the Ford F-150 or Chevrolet Silverado. Specific costs depend heavily on the model year, trim level, driver's profile, and geographic location, rather than the brand alone.
What factors make Toyota Tundra insurance more expensive?
Key factors that can increase Tundra insurance costs include a newer model year with advanced technology, a driver with a history of accidents or violations, living in an urban area with high theft rates, or opting for very low deductibles and extensive coverage add-ons.
Can I lower my Toyota Tundra insurance premium?
Yes, you can lower your Tundra insurance premium by maintaining a clean driving record, bundling policies, increasing your deductibles, installing anti-theft devices, and regularly comparing quotes from different insurance providers.
Does the Tundra's safety rating affect insurance costs?
Yes, the Toyota Tundra's strong safety ratings can positively influence insurance costs, particularly for coverages related to personal injury protection and medical payments, as it indicates a lower risk of severe injuries in an accident.