The Toyota Land Cruiser represents a significant investment, known for its robust build quality, off-road capability, and enduring resale value. Prospective and current owners often focus on the acquisition cost, maintenance, and fuel efficiency, but understanding the associated insurance premiums is equally critical for long-term financial planning. Insurance costs for a Land Cruiser are not uniform; they vary substantially based on the vehicle's specific model year, the driver's profile, geographic location, and the chosen coverage levels. Evaluating these factors upfront provides a clearer picture of the total ownership expense and helps in making informed decisions about coverage selection.
Key Factors Influencing Land Cruiser Insurance Premiums
Vehicle Value and Repair Costs
Land Cruisers command a premium price point, both new and on the used market, which directly impacts insurance premiums. A higher vehicle value translates to increased costs for comprehensive and collision coverage, as insurers face greater potential payouts for total loss or extensive repairs. Furthermore, the Land Cruiser's construction often involves specialized components and advanced technology, particularly in newer models. These parts can be more expensive to source and require specialized labor for repair, contributing to higher claim costs and, consequently, higher premiums.
Safety Features and Ratings
Modern Land Cruiser models incorporate advanced safety features such as pre-collision systems, lane departure alerts, adaptive cruise control, and multiple airbags. These technologies can mitigate accident severity and, in some cases, prevent collisions altogether, which may lead to lower insurance rates. Insurers assess the vehicle's safety ratings from organizations like the IIHS (Insurance Institute for Highway Safety) and NHTSA (National Highway Traffic Safety Administration). Vehicles with superior crash test performance and effective safety systems often qualify for more favorable premiums due to reduced risk of injury claims and vehicle damage.
Theft Rates
Certain vehicle models are more frequently targeted by thieves, and this risk is factored into insurance premiums. While specific theft rates for the Land Cruiser can vary by region and model year, its desirability and value can make it an attractive target. Insurers consider the likelihood of theft and the potential cost of replacing the vehicle when calculating comprehensive coverage rates. Installing approved anti-theft devices, such as alarms, immobilizers, or tracking systems, can sometimes lead to discounts on comprehensive coverage.
Driver Profile
The individual characteristics of the policyholder significantly influence insurance costs. Factors such as age, driving history, and claims record are primary determinants. Younger drivers, especially those under 25, typically face higher premiums due to statistical data indicating a greater risk of accidents. A history of traffic violations, at-fault accidents, or DUI convictions will also elevate rates. Additionally, an individual's credit-based insurance score (where permitted by state law) can play a role, with higher scores often correlating with lower premiums. Geographic location also matters; urban areas with higher traffic density, theft rates, or severe weather patterns generally have higher insurance costs.
Coverage Types
The specific types and limits of insurance coverage selected are paramount in determining the final premium. A basic liability-only policy will be less expensive than a full coverage policy, but it offers minimal protection for the insured vehicle.
- Liability Coverage: Required in most states, it covers damages and injuries to others if you are at fault in an accident.
- Collision Coverage: Pays for damage to your Land Cruiser resulting from a collision with another vehicle or object, regardless of fault.
- Comprehensive Coverage: Covers non-collision incidents such as theft, vandalism, fire, natural disasters, and animal impacts.
- Uninsured/Underinsured Motorist (UM/UIM) Coverage: Protects you if you're hit by a driver without sufficient insurance.
- Medical Payments/Personal Injury Protection (PIP): Covers medical expenses for you and your passengers, regardless of fault.
Opting for higher deductibles on collision and comprehensive coverage can reduce premiums, but it means a larger out-of-pocket expense in the event of a claim.
Understanding Land Cruiser Specifics
Older Models vs. Newer Models
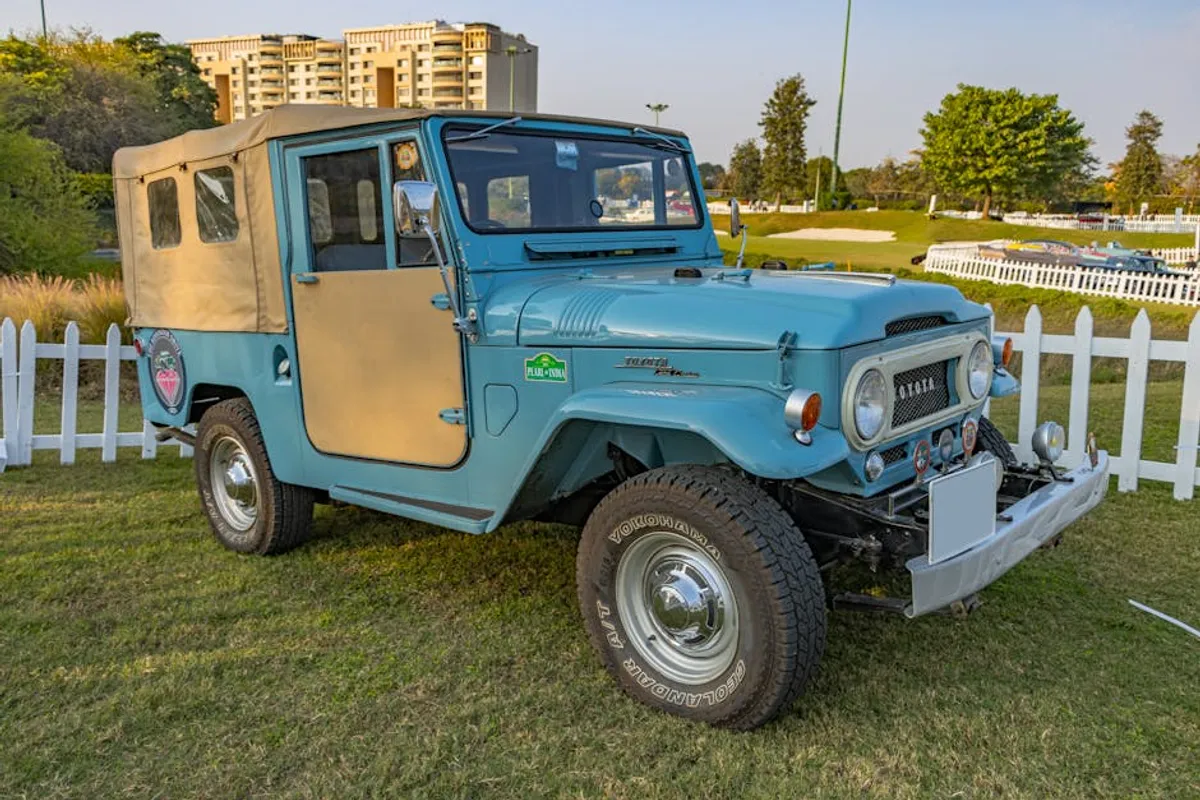
The age of your Land Cruiser can impact insurance rates in different ways. Older models, particularly those that have achieved classic status, might have lower collision and comprehensive premiums if their market value has depreciated significantly. However, parts for very old or rare models can be difficult to find and expensive, potentially offsetting some of those savings. Newer models, with their higher initial value and advanced technology, typically incur higher full-coverage premiums. Yet, they also benefit from modern safety features that can sometimes qualify for discounts.
Off-Road Modifications
Many Land Cruiser owners customize their vehicles for enhanced off-road performance with aftermarket parts like lift kits, larger tires, winches, and heavy-duty bumpers. These modifications often increase the vehicle's value and can alter its safety dynamics. It is crucial to inform your insurer about any significant modifications. Some insurers may not cover modified components under standard policies, or they might require specialized endorsement riders, which will increase the premium. Failing to disclose modifications could lead to claim denials.
Pro Tip: Before purchasing a Toyota Land Cruiser, especially a used model or one with existing modifications, obtain several insurance quotes using the exact VIN. This provides a realistic estimate of your future premiums and helps avoid unexpected costs. Be explicit about any non-factory additions when seeking quotes.
Strategies to Manage Land Cruiser Insurance Costs
Compare Quotes
Insurance premiums can vary widely between providers for the same coverage. It is advisable to obtain quotes from at least three to five different insurance companies. Each insurer uses proprietary algorithms to assess risk and set rates, so what one company considers high-risk, another might view differently. Online comparison tools and independent insurance agents can facilitate this process, ensuring you find the most competitive rates for your specific Land Cruiser model and driver profile.
Increase Deductibles
A deductible is the amount you pay out-of-pocket before your insurance coverage begins to pay for a claim. By choosing a higher deductible for your collision and comprehensive coverage (e.g., $1,000 instead of $500), you signal to the insurer that you are willing to bear a greater portion of minor repair costs. This typically results in a lower monthly or annual premium. However, ensure that you have sufficient emergency savings to cover the higher deductible if an incident occurs.
Seek Discounts
Most insurance companies offer a range of discounts that can significantly reduce your Land Cruiser's insurance costs. Common discounts include: bundling multiple policies (auto and home), multi-car discounts, good driver discounts for those with clean records, anti-theft device discounts, good student discounts (for younger drivers), and discounts for taking defensive driving courses. Inquire directly with your insurer about all available discounts for which you might qualify.
Maintain a Clean Driving Record
Your driving history is one of the most influential factors in determining insurance premiums. Avoiding traffic violations, speeding tickets, and at-fault accidents demonstrates responsible driving behavior. Insurers reward safe drivers with lower rates, often through "good driver" or "accident-free" discounts. A clean record over several years can lead to substantial long-term savings on your Land Cruiser's insurance.
Navigating Your Land Cruiser Insurance Options
Insuring a Toyota Land Cruiser involves balancing the vehicle's inherent value and performance characteristics with your personal risk profile and financial comfort. Proactive research into potential costs before purchase, coupled with diligent comparison shopping and strategic use of deductibles and discounts, forms the cornerstone of managing these expenses effectively. Regularly reviewing your policy and seeking new quotes, especially after major life events or changes to your driving record, ensures your coverage remains both adequate and cost-efficient. The goal is to secure comprehensive protection for your Land Cruiser without overpaying.
Frequently Asked Questions
Is Land Cruiser insurance more expensive than other SUVs?
Generally, yes. The Land Cruiser's higher MSRP, robust off-road capabilities (which can imply higher repair costs for specialized components), and desirability can lead to higher insurance premiums compared to many other mainstream SUVs. Its weight and power can also be factors in liability assessments.
Can I get classic car insurance for an older Land Cruiser?
Yes, many older Land Cruisers, particularly those from the FJ series or well-preserved 60, 80, or 100 series models, may qualify for classic or collector car insurance. These policies often have specific usage restrictions but can offer lower premiums and agreed-value coverage, which guarantees a payout for the vehicle's appraised value if it's a total loss.
Do anti-theft devices lower Land Cruiser insurance costs?
Yes, installing approved anti-theft devices such as vehicle recovery systems, alarm systems, or engine immobilizers can often lead to discounts on the comprehensive portion of your Land Cruiser's insurance policy. Check with your insurer for their specific requirements and eligible devices.
How does my location affect Land Cruiser insurance rates?
Your geographic location significantly impacts insurance rates. Urban areas with higher population density, increased traffic, higher crime rates (especially vehicle theft), and greater exposure to natural disasters (e.g., hail, hurricanes) typically incur higher premiums than rural areas. State-specific regulations and local claims history also play a role.