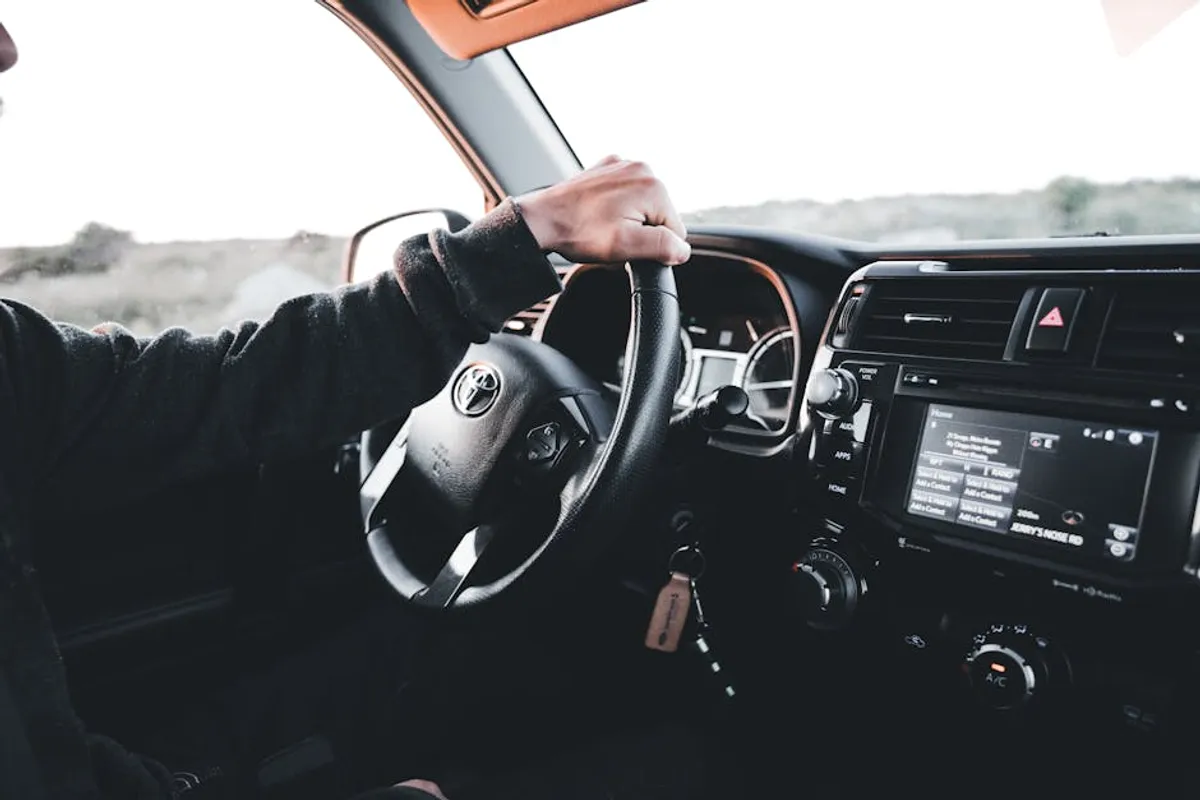
The Toyota 4Runner maintains a reputation for rugged durability and off-road capability, making it a popular choice for adventurers and families alike. However, the cost of insuring a 4Runner is a significant ownership consideration that prospective and current owners must understand. Insurance premiums are not static; they fluctuate based on a complex interplay of vehicle characteristics, driver demographics, and chosen coverage levels. Evaluating these elements provides a clearer picture of potential expenses.
Understanding Toyota 4Runner Insurance Premiums
Insurance companies assess risk to determine premiums. For the Toyota 4Runner, this assessment involves several factors specific to the vehicle itself, alongside the individual driver's profile.
Vehicle-Specific Factors Influencing 4Runner Rates
- Safety Ratings: High safety ratings often translate to lower insurance costs, as the likelihood of severe injury claims is reduced. The 4Runner consistently earns respectable safety scores, which can positively influence rates.
- Theft Rates: Vehicles frequently targeted by thieves typically incur higher comprehensive coverage costs. While 4Runners are popular, their theft rates generally fall within average ranges compared to some luxury SUVs or high-performance vehicles.
- Repair Costs and Parts Availability: The cost and availability of parts directly affect collision and comprehensive claims. The 4Runner's body-on-frame construction and widespread availability of parts, especially for common repairs, can help keep repair costs manageable. However, specialized off-road components or collision damage to structural elements can elevate expenses.
- Vehicle Value and Age: Newer, more expensive models naturally cost more to insure due to higher replacement or repair values. As a 4Runner ages, its market value decreases, potentially leading to lower comprehensive and collision premiums, assuming the owner maintains these coverages.
- Engine Size and Horsepower: While the 4Runner is not a performance vehicle, its V6 engine and weight contribute to its classification. Vehicles with higher horsepower or greater curb weight can sometimes be associated with higher accident severity, influencing rates.
Driver-Related Variables and Their Impact
Beyond the vehicle, individual driver characteristics heavily shape insurance premiums:
- Driving Record: A clean driving history with no accidents or moving violations is paramount for securing lower rates. Incidents like speeding tickets or at-fault collisions significantly increase premiums.
- Age and Experience: Younger, less experienced drivers typically face higher premiums due to statistical risk factors. As drivers gain experience and mature, rates generally decrease.
- Location: Urban areas with higher traffic density, crime rates, and greater risk of accidents or theft often result in higher premiums than rural areas. Specific zip codes within a city can also show variations.
- Credit Score: In many states, insurance companies use credit-based insurance scores as a factor in pricing policies. A higher credit score often correlates with lower premiums.
- Annual Mileage: Drivers who log fewer miles annually may qualify for low-mileage discounts, as their exposure to risk is reduced.
- Deductible Choice: Opting for a higher deductible on collision and comprehensive coverage lowers the premium, but requires the driver to pay more out-of-pocket in the event of a claim.
Typical Coverage Considerations for the 4Runner
The type and amount of coverage selected are primary determinants of the overall insurance cost.
Full Coverage Versus Liability-Only Options
Liability Coverage: This is legally required in most states and covers damages and injuries you cause to others in an at-fault accident. It does not cover your own vehicle or injuries.
Full Coverage: This term typically refers to a policy that includes liability, collision, and comprehensive coverage.
- Collision Coverage: Pays for damage to your 4Runner resulting from a collision with another vehicle or object, regardless of fault.
- Comprehensive Coverage: Covers damage to your 4Runner from non-collision events like theft, vandalism, fire, hail, or hitting an animal.
For newer 4Runners, especially those financed or leased, full coverage is almost always required by lenders. For older models, owners might consider dropping collision and comprehensive to save on premiums, but this means bearing the full financial risk of damage to their own vehicle.
Specific Coverage Add-ons to Evaluate
Beyond standard coverages, several add-ons can enhance protection but also increase costs:
- Uninsured/Underinsured Motorist Coverage: Protects you if you're hit by a driver with insufficient or no insurance.
- Roadside Assistance: Covers services like towing, flat tire changes, and jump-starts.
- Rental Car Reimbursement: Provides a rental car while your 4Runner is being repaired after a covered claim.
- Gap Insurance: Essential for financed or leased 4Runners. It covers the difference between what you owe on your loan and your vehicle's actual cash value if it's totaled.
Pro Tip: Many 4Runner owners customize their vehicles with aftermarket parts for off-roading or aesthetics. Standard insurance policies may not cover these modifications. Always inform your insurer about significant upgrades, such as lift kits, specialized bumpers, or roof racks, and inquire about specific endorsement options to ensure they are adequately covered in case of damage or theft.
Strategies to Manage 4Runner Insurance Expenses
Controlling insurance costs requires proactive steps:
- Shop Around and Compare Quotes: Insurance rates vary significantly between providers for the exact same coverage. Obtain quotes from multiple insurers annually to ensure you're getting the most competitive rates.
- Bundle Policies: Many insurers offer discounts for bundling auto insurance with other policies, such as home or renters insurance.
- Maintain a Clean Driving Record: Avoiding accidents and traffic violations is the most effective long-term strategy for keeping premiums low.
- Increase Your Deductible: If you have sufficient emergency savings, opting for a higher deductible can reduce your premium. Just ensure you can comfortably cover that deductible if a claim arises.
- Inquire About Discounts: Ask your agent about available discounts, which might include good student discounts, multi-car discounts, anti-theft device discounts, or discounts for completing defensive driving courses.
- Improve Your Credit Score: A strong credit history can positively impact your insurance rates in states where credit scores are used for pricing.
- Consider Telematics Programs: Some insurers offer programs that monitor your driving habits (speed, braking, mileage) via an app or device. Safe drivers can earn discounts.
Key Takeaways for 4Runner Owners
Insuring a Toyota 4Runner involves a balance between protecting a valuable asset and managing ongoing costs. Understanding the specific factors that influence premiums—from the 4Runner's robust build to your personal driving history—empowers you to make informed decisions. Regularly reviewing your policy, comparing quotes, and actively seeking discounts are essential practices for optimizing your insurance spend without compromising necessary protection. For those who customize their 4Runner, transparent communication with your insurer about modifications is critical to ensure proper coverage.
Frequently Asked Questions About 4Runner Insurance
Is the Toyota 4Runner expensive to insure compared to other SUVs?
The 4Runner's insurance costs are generally moderate. Its excellent safety ratings and reliability can help keep rates reasonable, but factors like its higher ground clearance and potential for off-road use (which might lead to specific types of claims) can influence premiums. It typically falls in the middle range when compared to luxury SUVs or high-performance vehicles.
What factors most significantly impact 4Runner insurance rates?
Key factors include your driving record, age, location, the specific trim level and year of your 4Runner, and the types and limits of coverage you choose. A clean driving history and a higher deductible are among the most impactful ways to potentially lower your premiums.
Can modifying my 4Runner affect my insurance?
Yes, significant modifications like lift kits, custom wheels, or performance upgrades can affect your insurance. These changes can increase the vehicle's value, alter its handling characteristics, or make it more appealing to thieves. It is crucial to disclose all modifications to your insurer and discuss specific coverage options or endorsements to ensure they are protected.
How can I save money on my Toyota 4Runner insurance?
To save money, compare quotes from multiple insurance providers regularly, bundle your auto policy with other insurance types, maintain a clean driving record, opt for a higher deductible if it's financially feasible, and inquire about all available discounts such as those for anti-theft devices or safe driving programs.