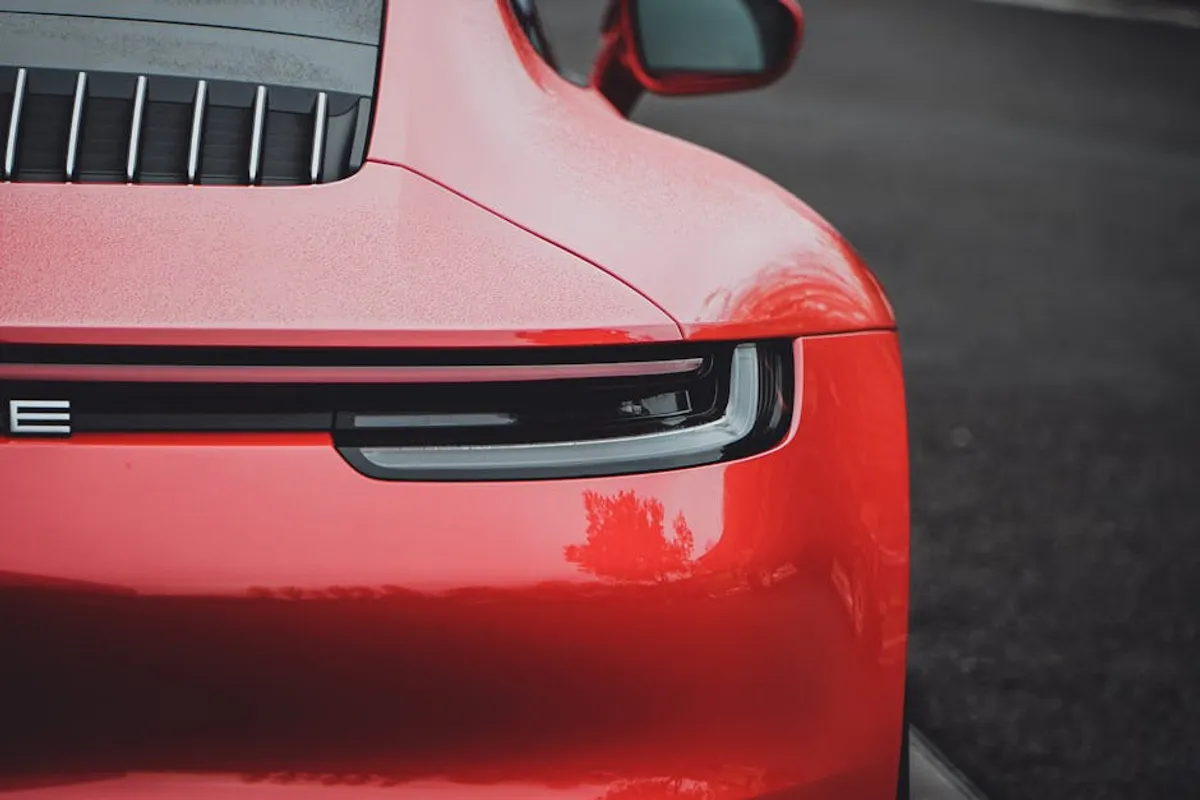
Acquiring a Porsche 911 represents a significant investment, and the associated insurance costs are a critical component of its total ownership expense. Drivers often focus on purchase price and maintenance, but insurance premiums can vary widely, impacting the overall financial feasibility of owning this iconic sports car. Understanding the specific factors that drive these costs, both inherent to the vehicle and unique to the driver, is essential for informed decision-making. This isn't a simple "average cost" calculation; it's a nuanced assessment of risk, performance, and coverage requirements that directly affects your annual outlay.
The Inherent Cost Drivers of Porsche 911 Insurance
Insurance providers assess risk based on several characteristics intrinsic to the Porsche 911 itself. These are not negotiable and form the baseline for any premium calculation.
Performance Capabilities and Accident Risk
The 911's performance is a primary cost driver. Its high-horsepower engines, rapid acceleration, and top-tier handling mean that in the event of an accident, the potential for high-speed impact and severe damage is elevated. Insurers factor in the statistical likelihood of such incidents and the resulting repair costs.
High Repair and Replacement Costs
Porsche vehicles, and the 911 in particular, utilize specialized materials, advanced engineering, and proprietary parts. Repairing even minor body damage can be expensive due to the cost of components and the specialized labor required. Furthermore, the high market value of a 911 means that total loss replacement costs are substantial, directly influencing comprehensive and collision coverage premiums.
Theft and Vandalism Appeal
As a high-value, desirable luxury sports car, the Porsche 911 is a target for theft and vandalism. Insurance companies account for this increased risk when setting rates, especially in areas with higher crime statistics. While modern 911s come with advanced anti-theft systems, the inherent appeal of the vehicle remains a factor.
Personalized Premium Factors: Your Profile and Location
Beyond the car's characteristics, your individual profile and circumstances significantly shape your insurance premium. These are variables you have some control over.
Driver History and Experience
A clean driving record, free of accidents, speeding tickets, or other moving violations, is paramount for securing lower rates. Insurers view experienced drivers with a history of safe driving as lower risk. Younger, less experienced drivers, even with a clean record, typically face higher premiums due to statistical risk profiles associated with age groups.
Geographic Location
Where you live and primarily garage your 911 has a direct impact. Urban areas with higher traffic density, greater rates of theft, or increased vandalism typically incur higher premiums than rural or suburban locales. Even specific zip codes within a city can show significant cost differences based on local claims data.
Annual Mileage and Usage
The more miles you drive your 911 annually, the higher the perceived risk of an incident. Using the car as a daily commuter versus an occasional weekend vehicle will result in different premium calculations. Some insurers offer discounts for low-mileage policies, especially for sports cars. Clarifying the primary usage (e.g., pleasure vs. commute) is important.
Credit Score and Financial Stability
In many regions, insurance providers use credit-based insurance scores as a predictor of future claims. A higher credit score often correlates with a lower perceived risk, potentially leading to more favorable rates. This factor reflects a broader assessment of financial responsibility.
Beyond Basic Coverage: Protecting Your 911 Investment
Standard liability coverage is a legal minimum, but a Porsche 911 demands more robust protection to safeguard your investment.
Comprehensive and Collision Coverage
These are non-negotiable for most 911 owners. Collision covers damage to your vehicle from an accident, regardless of fault. Comprehensive covers non-collision events like theft, vandalism, fire, natural disasters, and impacts with animals. Given the 911's value, these coverages carry substantial premiums but are critical for financial protection.
Agreed Value vs. Actual Cash Value
For high-value or classic 911 models, an "agreed value" policy can be beneficial. Unlike "actual cash value" (which depreciates the vehicle's worth over time), an agreed value policy pays out a pre-determined amount if the car is totaled or stolen, ensuring you receive its full market or appraised value. This is particularly relevant for limited editions or meticulously maintained older models.
Additional Endorsements to Consider
- Gap Insurance: Essential if you finance or lease your 911. It covers the difference between what you owe on the car and its actual cash value if it's totaled.
- New Car Replacement: For newer models, this covers the cost of a brand-new 911 of the same make and model if yours is totaled within a specified timeframe (e.g., first 1-3 years).
- OEM Parts Coverage: Ensures that repairs use original equipment manufacturer parts, maintaining the vehicle's integrity and value, rather than aftermarket alternatives.
- Roadside Assistance: While not unique to 911s, having specialized towing for a high-performance vehicle is practical.
Pro Tip: When obtaining quotes, specify if your 911 is a garage queen or a daily driver. Insurers may offer lower rates for vehicles driven less frequently, especially if you have another primary vehicle. Be precise about annual mileage estimates to ensure accurate pricing.
Navigating the Market: Reducing Your 911 Insurance Outlay
While 911 insurance will always be higher than for a standard sedan, there are proactive steps to manage and potentially reduce your premiums.
Bundling Policies
Many insurers offer discounts for bundling multiple policies, such as combining your 911 auto insurance with home, renters, or umbrella policies. This consolidates your insurance needs and can lead to significant savings across all lines.
Increasing Deductibles
Opting for a higher deductible on your comprehensive and collision coverage will lower your premium. This means you pay more out-of-pocket in the event of a claim, so ensure your deductible is an amount you can comfortably afford.
Security and Safety Features
Installing approved anti-theft devices, GPS trackers, or even having a secure, locked garage can qualify you for discounts. Some insurers also recognize advanced driver-assistance systems (ADAS) present in newer 911s, though the impact on premiums can vary.
Maintaining a Strong Driving Record
Consistently driving safely and avoiding traffic violations is the most effective long-term strategy for keeping insurance costs down. A clean record demonstrates a lower risk profile to insurers.
Model Variance: How Specific 911 Trims Impact Rates
Not all 911 models are insured equally. The specific trim, engine, and performance enhancements play a role in premium differentiation.
For instance, a base Carrera might have lower premiums than a high-performance Turbo S or a track-focused GT3. The latter models, with their increased horsepower, higher top speeds, and specialized components, present a greater risk profile for insurers. Limited production models or those with unique features might also command specific underwriting considerations.
Securing the Right Policy for Your Porsche 911
Insuring a Porsche 911 requires diligence. Begin by gathering detailed information about your specific model, including year, trim, and any aftermarket modifications. Be prepared to provide a comprehensive overview of your driving history and where the vehicle will be stored. Obtain quotes from multiple insurers, specifically those with experience insuring high-performance and luxury vehicles. Compare not just the premium, but also the coverage limits, deductibles, and any specific endorsements that align with your needs. The goal is to balance cost with adequate protection for your significant investment.
Common Questions on Porsche 911 Insurance
Is Porsche 911 insurance always significantly more expensive?
Yes, compared to standard vehicles, 911 insurance is generally more expensive due to its high performance, high repair costs, and desirability as a theft target. However, the exact premium depends heavily on individual factors and chosen coverage.
Does the age of the 911 affect insurance costs?
Typically, newer 911 models (e.g., 992 generation) might have higher premiums for collision and comprehensive due to their higher replacement value and advanced technology. Older, classic 911s might qualify for specialized classic car insurance, which can sometimes be less expensive than standard policies, provided they are driven sparingly and stored securely.
Can I get a discount for taking a defensive driving course?
Many insurance providers offer discounts for completing approved defensive driving courses, especially for younger drivers or those looking to offset minor infractions. It's worth inquiring with your insurer about their specific programs and eligibility.
What if I modify my Porsche 911?
Any significant aftermarket modifications, especially those enhancing performance or altering the vehicle's value, must be disclosed to your insurer. Failure to do so could lead to claims being denied. Some modifications may increase premiums, while others (like certain security upgrades) might offer discounts.