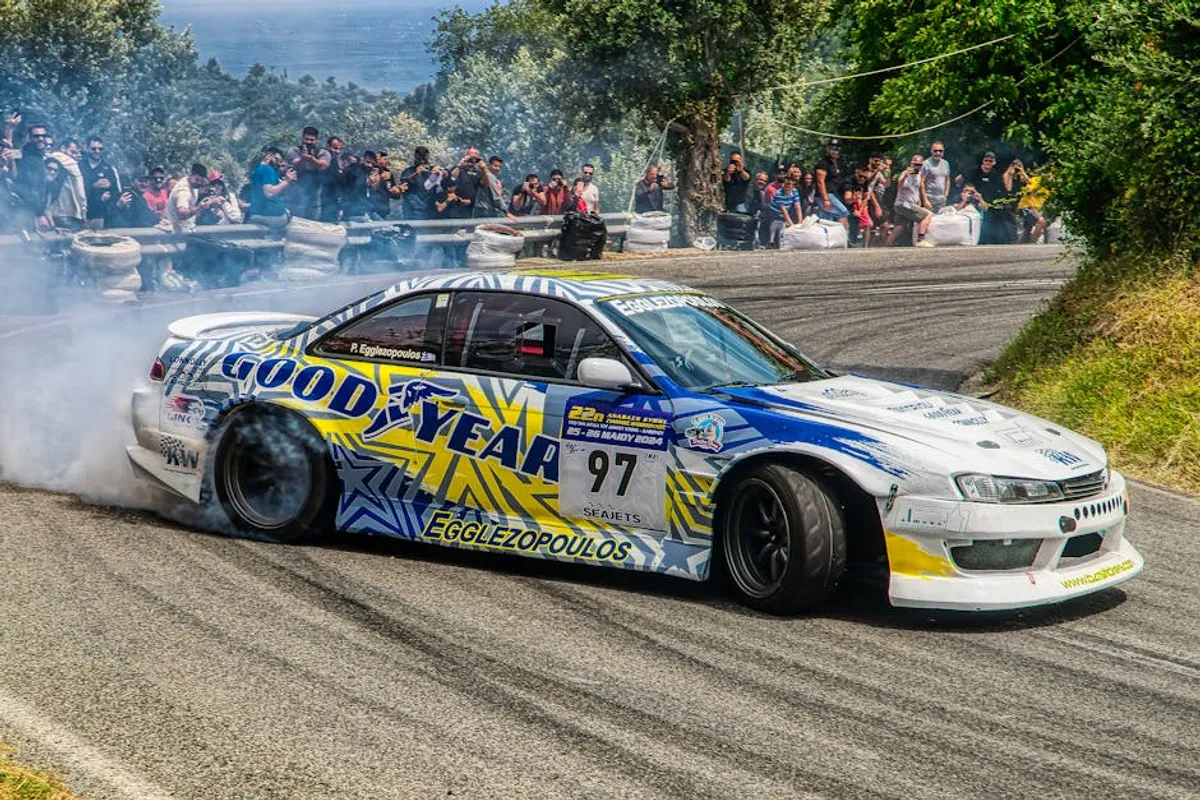
For enthusiasts considering a Nissan Silvia, understanding the associated insurance costs is as critical as evaluating the vehicle's performance or condition. These vehicles, particularly popular for their tuning potential and drifting heritage, often present a unique risk profile to insurers. This profile translates directly into premiums that can differ significantly from those of more conventional vehicles. Prospective and current owners need to grasp the specific factors that influence these costs, allowing for informed decisions on purchasing, modifying, and insuring their Silvia.
Understanding the Nissan Silvia's Insurance Profile
The Nissan Silvia series (S13, S14, S15 models being the most recognized) carries a distinct insurance classification due to several inherent characteristics. Insurers assess risk based on statistical data related to accident rates, theft rates, repair costs, and performance capabilities. For the Silvia, these factors converge to create a specific underwriting challenge:
- Performance Designation: Silvias are rear-wheel-drive sports coupes, often equipped with turbocharged engines (e.g., SR20DET). This performance potential places them in a higher risk category than standard passenger cars, correlating with increased likelihood of high-speed incidents.
- Modification Appeal: A significant percentage of Silvias are modified for performance, aesthetics, or track use. Modifications can increase vehicle value, alter handling characteristics, and complicate repair processes, all of which elevate insurance risk. Non-declared modifications can lead to policy invalidation.
- Theft Risk: Due to their desirability among enthusiasts and for parts, Silvias can be targets for theft. This heightened risk drives up premiums, especially in urban areas or regions with higher vehicle crime rates.
- Parts Availability and Cost: Depending on the specific model and region, sourcing genuine or specialized parts for repairs can be challenging or expensive. This affects an insurer's potential payout for repairs, influencing premium calculations.
Key Variables Affecting Your Premium
Vehicle Specifics: Age, Model, and Modifications
The exact Silvia model and its age play a role. Older models might qualify for classic or specialist policies, which can sometimes offer lower premiums if strict conditions (e.g., limited mileage, garaged storage) are met. However, the S15, being newer and often more powerful, typically commands higher rates. Critically, any modifications, from engine tunes to suspension upgrades or body kits, must be declared. Failure to do so can lead to a policy being nullified in the event of a claim. Insurers often view modifications as increasing risk, either by enhancing performance beyond factory specifications or by making the vehicle more attractive to thieves.
Driver Profile: Experience, Record, and Location
Your personal driving history is paramount. Younger drivers, especially those under 25, face significantly higher premiums due to statistical data linking age and inexperience to higher accident rates. A clean driving record, free of accidents, speeding tickets, or other infractions, is essential for securing competitive rates. Your geographic location also matters; areas with higher population density, higher crime rates, or greater traffic congestion typically result in increased premiums. Where the vehicle is parked overnight (e.g., secure garage versus street parking) is also a factor.
Coverage Choices and Deductibles
The type and extent of coverage you select directly impact your premium. Comprehensive policies, which cover damage to your vehicle from various sources (theft, vandalism, natural disasters) in addition to collision, are more expensive than basic liability-only coverage. Opting for higher deductibles (the amount you pay out-of-pocket before insurance coverage begins) can lower your premium, but requires you to absorb more of the initial repair cost in a claim scenario. Carefully consider the trade-off between premium savings and potential out-of-pocket expenses.
Pro Tip: Always declare all modifications to your insurer, no matter how minor they seem. Undisclosed modifications can lead to your policy being voided, leaving you fully responsible for repair costs and third-party damages in the event of an accident. Specialist insurers are often more accommodating and understanding of modified vehicles than standard providers.
Navigating Specialist Insurance Markets
Standard insurance providers may offer limited options or prohibitively high premiums for Nissan Silvias, especially modified examples. This is where specialist insurers and brokers become invaluable. These companies often have dedicated departments or policies tailored for performance, imported, or modified vehicles. They understand the nuances of the enthusiast market and can offer more appropriate coverage, sometimes at a more competitive rate, because they accurately assess the specific risks rather than applying broad, conservative categories.
When engaging with specialist providers, be prepared to furnish detailed information:
- Exact vehicle specifications, including engine code and VIN.
- A comprehensive list of all modifications, including parts brands and installation dates.
- Details of any security devices installed.
- Your driving history and any advanced driving qualifications.
- Intended vehicle usage (e.g., daily driver, weekend car, track days).
Strategies to Manage Nissan Silvia Insurance Costs
Prioritize Security Enhancements
Installing approved security devices can significantly reduce theft risk and, consequently, your premium. Options include Thatcham-approved alarms, immobilizers, tracking devices, and secure garaging. Document these installations with receipts and certificates to present to your insurer.
Maintain a Clean Driving History
A consistent record of safe driving is the most impactful long-term strategy for lower premiums. Avoid speeding tickets, at-fault accidents, and other moving violations. Some insurers offer "no-claims discounts" that accumulate over years of incident-free driving.
Consider Agreed Value Policies for Modifications
If your Silvia is heavily modified, a standard policy might only cover its market value as a stock vehicle, leaving you underinsured for your investment in parts and labor. An "agreed value" policy allows you and the insurer to agree on a specific valuation for your vehicle, including modifications, ensuring you receive a fair payout if it's written off or stolen. This often requires professional appraisals and detailed documentation of all modifications.
Shop Around with Specialist Brokers
Do not settle for the first quote. Engage multiple specialist brokers who understand performance and imported vehicles. They have access to a wider range of underwriters and policies designed for cars like the Silvia, increasing your chances of finding competitive coverage tailored to your specific needs.
Actionable Steps for Silvia Owners
Before committing to a Nissan Silvia or renewing your policy, gather all relevant information about the vehicle and your driving history. Contact several specialist insurance providers and brokers, providing them with a complete and accurate picture. Be transparent about any modifications, even minor ones, to ensure your policy remains valid. Explore options for security enhancements and understand how different coverage levels and deductibles impact your overall cost. Proactive research and clear communication with insurers are key to securing appropriate and affordable coverage for your Silvia.
Frequently Asked Questions
Why is Nissan Silvia insurance often higher than for other cars?
Nissan Silvias are classified as performance sports coupes, often targeted for theft, and frequently modified for increased power or track use. These factors collectively elevate the perceived risk for insurers, leading to higher premiums compared to standard vehicles.
Can I get classic car insurance for my Nissan Silvia?
Some older Silvia models, particularly the S13 and S14, may qualify for classic or specialist enthusiast insurance if they meet specific criteria, such as limited annual mileage, garaged storage, and original or period-correct condition. Eligibility varies by insurer and region.
Do modifications void my Nissan Silvia insurance policy?
Undisclosed modifications can void your insurance policy. It is crucial to declare all modifications to your insurer. While some modifications might increase your premium, failing to declare them can result in no payout in the event of a claim, leaving you financially exposed.
What type of coverage is recommended for a Nissan Silvia?
For a valuable or modified Nissan Silvia, comprehensive coverage is generally recommended. Additionally, consider an "agreed value" policy if your vehicle has significant modifications or a value beyond its standard market rate, to ensure adequate compensation in case of a total loss.