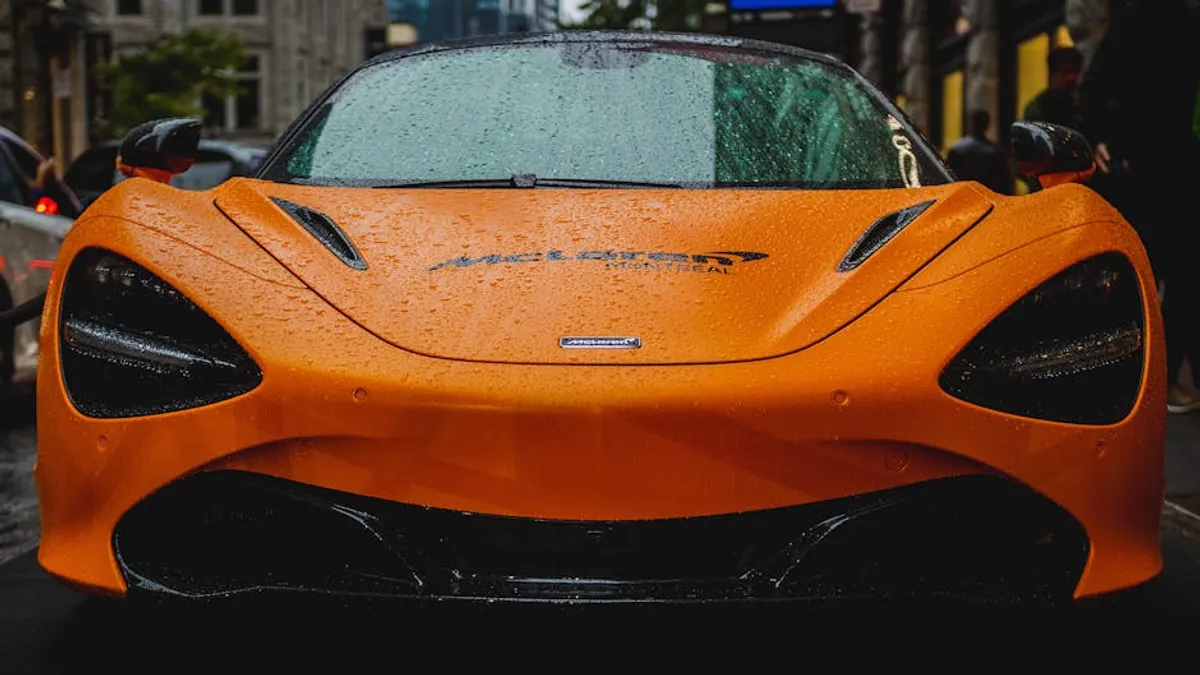
Insuring a McLaren F1 is not a standard automotive transaction; it is a highly specialized financial commitment reflecting the vehicle's extreme rarity, performance capabilities, and multi-million dollar valuation. Owners and prospective buyers must approach this process with a clear understanding that conventional insurance models are insufficient. The objective is to secure comprehensive protection that accounts for the vehicle's unique attributes, driver profile, and intended use, often requiring bespoke policies from specialist providers.
Core Determinants of McLaren F1 Insurance Premiums
Several critical factors converge to define the insurance cost for a McLaren F1. These elements are assessed rigorously by underwriters to quantify risk and establish appropriate coverage:
- Vehicle Value and Rarity: The McLaren F1’s status as a limited-production hypercar, with values frequently exceeding $20 million, directly translates to elevated premiums. The cost of total loss or significant repair, involving custom-fabricated parts and specialized labor, is exceptionally high.
- Performance Specifications: With a top speed over 240 mph and rapid acceleration, the F1 presents an inherent risk profile. Insurers account for the potential for high-speed incidents and the resulting damage severity.
- Parts Availability and Repair Complexity: Components are bespoke and no longer in production, necessitating either custom fabrication or sourcing from a finite supply of original parts. This complexity drives up repair costs and extends repair times, increasing potential loss of use.
- Driver Profile and Experience: The policyholder's driving history, age, experience with high-performance vehicles, and claims record are paramount. A clean record and demonstrated competence in handling high-powered cars are essential for securing favorable terms.
- Intended Usage: Whether the F1 is primarily a garage queen, a show car, or sees occasional road use significantly impacts risk. Track day participation, even infrequent, often requires specific endorsements or separate policies dueating to the heightened risk of competitive driving environments.
- Storage and Security: Insurers mandate secure storage. This typically means a climate-controlled, alarm-equipped private garage. Advanced tracking systems and professional security measures can mitigate theft risk and may influence premiums.
- Geographic Location: The primary storage location and areas of intended use are evaluated for theft rates, accident frequency, and population density. High-risk urban areas or regions with adverse weather conditions can lead to higher costs.
Specialized Coverage Options for Hypercar Ownership
Standard auto insurance policies are inadequate for a McLaren F1. Owners require highly specialized coverage tailored to the vehicle's unique profile:
Agreed Value Policies: This is a non-negotiable requirement for hypercars. Instead of a depreciated actual cash value, the insurer and owner agree upon a fixed valuation for the vehicle at the policy's inception. In the event of a total loss, this agreed amount is paid out, providing financial certainty. This protects against market fluctuations and the subjective nature of classic car valuations.
Limited Mileage Provisions: Many McLaren F1 owners drive their vehicles sparingly. Policies can be structured with annual mileage limits, which often reduce premiums by reflecting lower exposure to road risks. Exceeding these limits without notification can void coverage.
Track Day Endorsements: Standard policies almost universally exclude damage incurred during competitive events, timed runs, or track days. Owners who intend to use their F1 on a circuit must secure a separate track day policy or a specific endorsement from a specialist insurer. These policies are typically short-term and carry higher deductibles.
Overseas Transit and Storage: For collectors who move their F1 internationally for shows, events, or storage, specialized transit and marine cargo insurance is necessary. This covers risks associated with shipping, port handling, and temporary storage abroad.
Concierge Claims Services: Specialist insurers often provide dedicated claims handlers experienced with high-value vehicles. This ensures a streamlined process, access to approved repair facilities, and expertise in sourcing rare parts.
Pro Tip: Never understate your intended usage or fail to disclose modifications. Specialist hypercar insurance policies are built on precise risk assessment. Any material misrepresentation, such as omitting track use or significant performance upgrades, can lead to a denial of claims, rendering your multi-million dollar asset uninsured when it matters most.
Strategies for Optimizing McLaren F1 Insurance Costs
While McLaren F1 insurance will always be substantial, owners can employ specific strategies to manage premiums effectively:
Engage Specialist Brokers: Traditional insurance agents rarely possess the expertise or access to underwriters required for hypercars. Work exclusively with brokers specializing in high-net-worth individuals and classic/exotic vehicles. They understand the nuances of agreed value, limited mileage, and bespoke coverage, and can access a wider network of niche insurers.
Maintain an Impeccable Driving Record: A history of speeding tickets, accidents, or other infractions will significantly increase premiums or even lead to refusal of coverage. For a vehicle of the F1's caliber, a pristine driving record is non-negotiable.
Enhance Security Measures: Beyond a secure garage, consider additional layers of protection. This includes advanced GPS tracking systems with geofencing capabilities, motion-activated surveillance, and professional security services if the vehicle is stored in a less private setting. Document these measures for your insurer.
Consider Higher Deductibles: Opting for a higher deductible can reduce the overall premium. However, this strategy requires careful financial planning, as the deductible for a hypercar could still be tens or hundreds of thousands of dollars. Ensure you have readily available funds to cover this amount should a claim arise.
Annual Policy Review: Market values for McLaren F1s can fluctuate. Conduct an annual review with your broker to ensure the agreed value remains appropriate and that your coverage still aligns with your usage patterns and any changes in the vehicle's condition or modifications.
Navigating the McLaren F1 Insurance Market
Securing insurance for a McLaren F1 demands a proactive and informed approach. It is a process that begins well before vehicle acquisition, often requiring pre-approval from specialist insurers. The market for such policies is small, highly specialized, and relationship-driven. Expect detailed questionnaires regarding your driving history, financial standing, and the specifics of the vehicle's storage and intended use. The objective is not merely to find the cheapest policy, but the most comprehensive and reliable coverage from an underwriter with proven experience in the hypercar segment.
Frequently Asked Questions About McLaren F1 Insurance
Q: How much does McLaren F1 insurance typically cost annually?
A: Annual premiums for a McLaren F1 can range from $30,000 to over $100,000, depending on the agreed value, driver profile, usage, and chosen coverage. This is a highly variable figure, and a precise quote requires individual assessment.
Q: Can I use a standard auto insurance company for my McLaren F1?
A: No, standard auto insurance companies are not equipped to underwrite or service policies for vehicles like the McLaren F1. You will need a specialist insurer or broker who deals exclusively with high-value, exotic, and classic cars.
Q: Does track use void my McLaren F1 insurance?
A: Most standard and even specialist hypercar policies explicitly exclude track use, competitive driving, or timed events. Engaging in these activities without a specific track day endorsement or separate policy will almost certainly void coverage for any damage incurred.
Q: What is "agreed value" insurance and why is it crucial for a McLaren F1?
A: Agreed value insurance means you and the insurer agree on the vehicle's worth at the policy's start. In a total loss, you receive that agreed amount. It's crucial for an F1 because its market value is unique and not easily determined by standard depreciation tables, protecting your investment against subjective valuation.