Drivers considering hybrid vehicles often face questions regarding insurance costs. The perception that hybrids are inherently more expensive or cheaper to insure than their gasoline-powered counterparts is not always straightforward. Insurance premiums for hybrid cars are determined by a complex interplay of factors, including the vehicle's specific technology, repair costs, safety features, and the driver's profile. Understanding these variables is crucial for accurately forecasting expenses and making informed coverage decisions before purchasing a hybrid model.
Understanding Hybrid Vehicle Insurance Premiums
Hybrid car insurance premiums are not universally higher or lower than those for traditional internal combustion engine (ICE) vehicles. The cost is highly individualized, reflecting both the vehicle's characteristics and the policyholder's risk profile. While hybrids often incorporate advanced technology and specialized components, which can drive up repair costs, they also tend to have better fuel efficiency and lower emissions, sometimes qualifying for specific discounts.
The primary consideration for insurers is risk assessment. This includes the likelihood of an accident, the potential cost of repairs or replacement, and the risk of theft. For hybrids, the unique powertrain and battery systems introduce distinct repair considerations that can impact premium calculations.
Key Factors Influencing Hybrid Car Insurance Rates
Vehicle-Specific Considerations
The make, model, and year of a hybrid vehicle play a significant role in insurance pricing. Factors include:
- Purchase Price and Replacement Cost: Higher sticker prices, common for newer hybrid models, translate to higher replacement costs for insurers, thus increasing premiums.
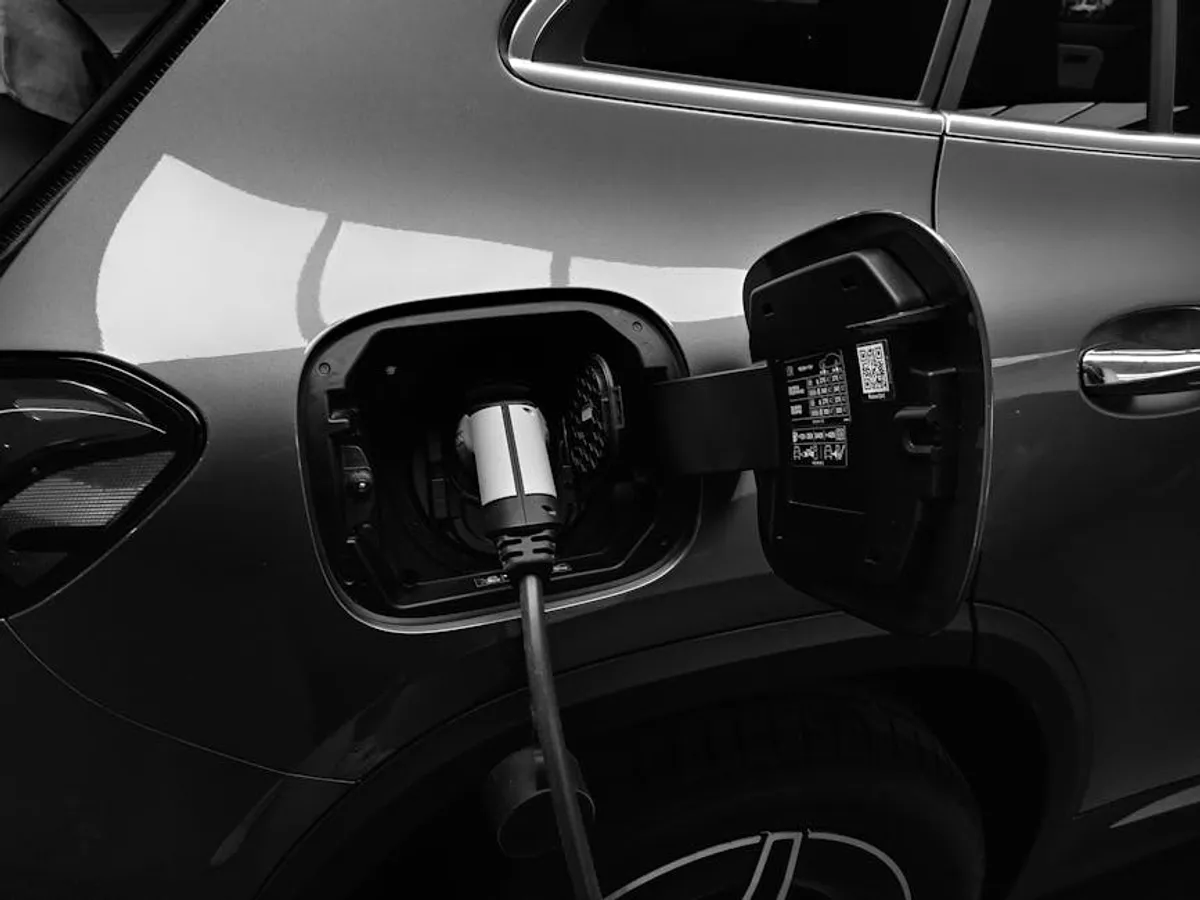
- Repair Complexity and Parts Cost: Hybrid vehicles often feature sophisticated electrical systems, specialized batteries, and integrated powertrains. Repairs can require specialized technicians and more expensive parts, particularly for battery replacement or damage to the hybrid system.
- Safety Features: Many newer hybrids come equipped with advanced driver-assistance systems (ADAS) like automatic emergency braking, lane-keeping assist, and adaptive cruise control. These features can reduce accident risk, potentially lowering premiums, but their repair or recalibration after a collision can be costly.
- Theft Rates: Certain hybrid models may be more or less attractive to thieves. Insurers track theft data, and models with higher theft rates typically incur higher comprehensive coverage costs.
- Performance and Horsepower: Vehicles with higher performance capabilities, even hybrids, can sometimes be associated with higher accident risks, influencing rates.
Driver-Specific Variables
Beyond the vehicle itself, the policyholder's characteristics are critical determinants of insurance costs:
- Driving Record: A clean driving history with no accidents or violations consistently results in lower premiums. Conversely, past incidents will elevate costs.
- Age and Experience: Younger, less experienced drivers generally face higher rates due to statistical accident risk.
- Location: Urban areas with higher traffic density, crime rates, and accident frequency typically have higher insurance costs than rural areas.
- Credit Score: In many states, insurers use credit-based insurance scores as a predictor of claim likelihood, with higher scores often leading to lower premiums.
- Annual Mileage: Drivers who cover fewer miles annually may qualify for lower rates, as less time on the road statistically reduces accident exposure.
Coverage Level Impact
The types and limits of coverage selected directly affect the premium. Basic liability coverage is legally mandated, but additional coverages like collision, comprehensive, uninsured/underinsured motorist, and medical payments coverage add to the total cost. Higher deductibles on collision and comprehensive coverage can reduce premiums, but require the driver to pay more out-of-pocket in the event of a claim.
Comparing Hybrid and Conventional Vehicle Insurance
Historically, some hybrid models faced higher insurance costs due to the novelty and perceived complexity of their technology. However, as hybrid technology has become more mainstream and repair processes have evolved, this gap has often narrowed or even reversed for certain models. The key differentiator remains the specific model's repair costs and safety ratings, rather than simply its hybrid status.
For instance, a hybrid variant of a popular sedan might have similar insurance costs to its gasoline counterpart if their repair profiles and safety features are comparable. Conversely, a luxury performance hybrid with expensive components could cost significantly more to insure than a basic conventional vehicle.
Pro Tip: When evaluating a hybrid vehicle, obtain insurance quotes for the specific make and model before finalizing your purchase. Compare these quotes not only against other hybrid models but also against conventional vehicles you are considering. This direct comparison provides the most accurate picture of potential insurance costs.
Discounts Specific to Hybrid Vehicle Ownership
Some insurance providers offer specific discounts for owning an environmentally friendly vehicle, including hybrids. These can include:
- Green Vehicle Discounts: A percentage off the premium for owning a hybrid or electric vehicle.
- Low Mileage Discounts: Hybrids often achieve better fuel economy, which can lead to lower annual mileage for some drivers, qualifying them for mileage-based discounts.
- Safety Feature Discounts: Many hybrids come standard with advanced safety features (e.g., anti-lock brakes, electronic stability control, multiple airbags) that can earn discounts.
- Multi-Policy Discounts: Bundling car insurance with home or renters insurance often results in overall savings.
Strategies for Optimizing Hybrid Car Insurance Costs
Drivers can proactively manage their hybrid car insurance expenses through several methods:
- Shop Around Annually: Insurance rates vary significantly between providers. Obtaining quotes from multiple insurers each year can identify more competitive rates for your specific hybrid model and driver profile.
- Maintain a Clean Driving Record: Avoiding accidents and traffic violations is the most impactful way to keep premiums low over time.
- Increase Deductibles: Opting for higher deductibles on collision and comprehensive coverage can reduce your premium, but ensure you can comfortably afford the out-of-pocket expense if a claim arises.
- Take Advantage of Discounts: Inquire about all available discounts, including those for green vehicles, good students, defensive driving courses, and bundling policies.
- Improve Credit Score: A higher credit-based insurance score can lead to lower premiums in states where this is permitted.
- Consider Telematics Programs: Some insurers offer programs that monitor driving habits (e.g., mileage, speed, braking) via a smartphone app or device, potentially rewarding safe drivers with lower rates.
Securing Your Hybrid Car Insurance Policy
The decision to purchase a hybrid vehicle involves evaluating more than just the sticker price and fuel economy. Insurance costs represent a significant ongoing expense that requires careful consideration. By understanding the specific factors that influence hybrid car insurance premiums—from the vehicle's technology and repair complexity to your personal driving history and chosen coverage levels—you can approach the process with clarity. Proactive research, comparing multiple quotes, and leveraging available discounts are essential steps to securing appropriate coverage at a competitive rate for your hybrid vehicle.
Frequently Asked Questions About Hybrid Car Insurance
Are hybrid cars always more expensive to insure?
No, not always. While some hybrids may have higher repair costs due to specialized components, many also offer advanced safety features and fuel efficiency that can lead to discounts. Insurance costs depend on the specific model, driver profile, and chosen coverage.
Can I get discounts for owning a hybrid vehicle?
Yes, many insurance providers offer "green vehicle" or "eco-friendly" discounts for hybrid owners. Additionally, hybrids often qualify for low mileage discounts due to better fuel efficiency, and standard safety feature discounts apply.
Do insurance companies treat hybrid battery replacement differently?
Insurance policies typically cover damage to hybrid batteries under collision or comprehensive coverage, similar to other vehicle components, if the damage is due to a covered event. However, the high cost of hybrid battery replacement can contribute to higher overall repair costs and influence premiums.
What is the best way to find affordable hybrid car insurance?
The most effective strategy is to compare quotes from multiple insurance companies annually. Also, maintain a clean driving record, inquire about all eligible discounts, and consider adjusting your deductibles to find a balance between premium cost and out-of-pocket expenses.