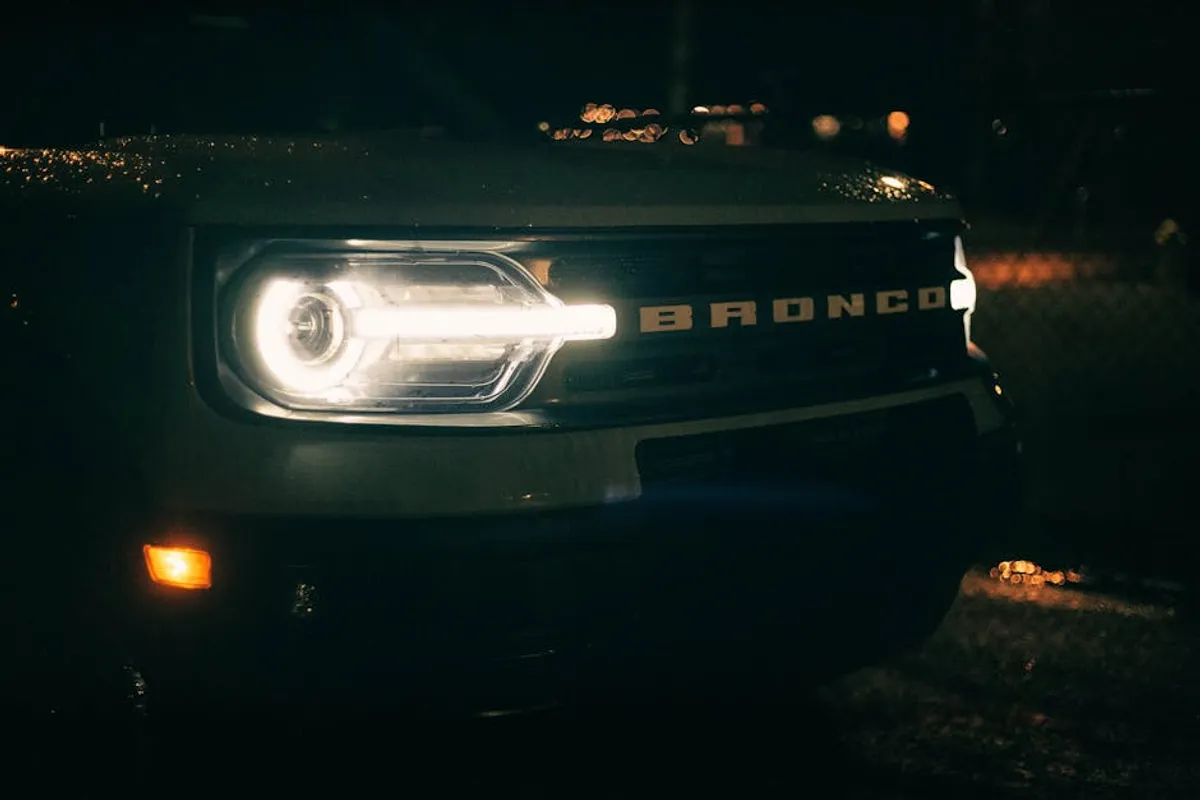
Understanding Ford Bronco insurance costs requires a detailed look at factors beyond a standard vehicle. The Bronco, known for its rugged design, off-road prowess, and modular components, often incurs higher insurance premiums compared to more conventional SUVs. This is due to a combination of its purchase price, repair complexity, potential for theft, and the driving behaviors it encourages. For prospective and current owners, recognizing these influences is crucial for budgeting and securing appropriate coverage. This guide outlines the specific elements that drive Bronco insurance rates and offers actionable strategies to manage those expenses effectively.
Understanding Ford Bronco Insurance Premiums
Ford Bronco insurance premiums are not static; they fluctuate based on a detailed assessment of the vehicle itself, the driver's profile, and the chosen coverage levels. Identifying these core variables helps in predicting and ultimately influencing your annual costs.
Vehicle-Specific Cost Drivers
The Bronco's design and market position significantly impact its insurance profile. Its higher Manufacturer's Suggested Retail Price (MSRP) directly correlates with increased comprehensive and collision coverage costs, as insurers must cover a greater potential loss. Beyond the initial price, the vehicle's unique construction plays a role:
- Repair Complexity: The Bronco's modular design, including removable doors and roof panels, can lead to more intricate and expensive repairs after an accident. Specialized parts and labor for these components increase the cost of claims.
- Theft Rates: Popular, desirable vehicles, especially those with removable parts, can sometimes face higher theft risks. Insurers factor in regional theft statistics for specific models when calculating comprehensive coverage.
- Performance and Off-Road Capability: While not a sports car, the Bronco's off-road capabilities might be perceived by some insurers as encouraging higher-risk driving, potentially leading to increased collision claims. Certain trims with more powerful engines or specialized off-road equipment can also influence rates.
- Safety Ratings: While modern vehicles generally have strong safety features, the Bronco's specific crash test ratings (when available for all configurations) and real-world accident data contribute to its risk profile.
Driver Profile and Geographic Impact
Your personal details and where you live are equally significant in determining insurance rates:
- Age and Driving Record: Younger, less experienced drivers or those with a history of accidents or traffic violations typically face higher premiums due to increased perceived risk. A clean driving record consistently lowers costs.
- Location: Urban areas with higher traffic density, crime rates, and greater incidence of accidents generally result in higher premiums than rural or suburban locales. Specific zip codes within a city can also have varying rates.
- Credit Score: In many states, insurers use credit-based insurance scores as a predictor of claim likelihood. A higher score often translates to lower premiums.
- Annual Mileage: Drivers who log fewer miles annually may qualify for discounts, as less time on the road theoretically reduces accident exposure.
The Role of Coverage Choices
The types and limits of coverage you select are direct determinants of your overall premium. State minimums are often insufficient for proper protection, especially with a vehicle like the Bronco.
Liability Coverage: This covers damages and injuries you cause to others. Higher limits, while costing more, provide essential financial protection against large claims.
Collision Coverage: Pays for damage to your Bronco resulting from a collision with another vehicle or object, regardless of fault. This is often the most expensive component of a policy for a new vehicle.
Comprehensive Coverage: Covers non-collision damage, such as theft, vandalism, fire, weather events, and impacts with animals. Given the Bronco's appeal and modular design, this coverage is critical.
Uninsured/Underinsured Motorist (UM/UIM): Protects you if you're involved in an accident with a driver who has insufficient or no insurance.
Additional Coverages: Options like roadside assistance, rental car reimbursement, and custom parts and equipment coverage (important for modified Broncos) add to the premium but offer valuable protection.
Strategies to Manage Bronco Insurance Expenses
While some factors are fixed, drivers have several avenues to actively reduce their Ford Bronco insurance costs without compromising essential protection.
Smart Shopping and Policy Adjustments
The most direct way to find competitive rates is through diligent comparison. Insurance providers use different proprietary algorithms to assess risk, leading to significant price variations for the same coverage.
- Compare Quotes Annually: Obtain quotes from multiple insurers at least once a year, or whenever your policy is up for renewal. Online comparison tools and independent agents can streamline this process.
- Adjust Deductibles: Increasing your collision and comprehensive deductibles (the amount you pay out-of-pocket before insurance kicks in) will lower your premium. Ensure you can comfortably afford the higher deductible in case of a claim.
- Review Coverage Needs: As your Bronco ages, or if your financial situation changes, re-evaluate the necessity of certain coverages. For instance, if your vehicle is older and fully paid off, you might consider dropping collision or comprehensive if the premium outweighs the vehicle's market value.
Leveraging Discounts and Safety Features
Many insurers offer a range of discounts that can significantly reduce your premium. It's important to ask about every available option.
Multi-Policy Discounts: Bundling your auto insurance with homeowner's, renter's, or life insurance often results in a substantial discount on all policies.
Good Driver/Clean Record Discounts: Maintaining a clean driving record free of accidents or violations for a specified period (e.g., three to five years) is a key factor in lowering rates.
Anti-Theft Devices: Installing approved anti-theft systems (alarms, tracking devices) can qualify for discounts, particularly relevant for a vehicle like the Bronco with potential theft appeal.
Safety Features: Modern Broncos come equipped with advanced safety features (e.g., automatic emergency braking, lane-keeping assist). Ensure your insurer is aware of these to potentially apply safety feature discounts.
Defensive Driving Courses: Completing an approved defensive driving course can sometimes lead to a discount, especially for younger or older drivers.
Pro Tip: Be transparent with your insurer about your Bronco's primary use. If it's a weekend vehicle or used for significantly fewer miles than average, inquire about low-mileage or leisure-use discounts. However, accurately report usage; misrepresenting mileage can lead to claim denials.
Final Considerations for Bronco Owners
Owning a Ford Bronco is an investment that extends beyond the purchase price. Proactively managing your insurance costs involves understanding the unique risk factors associated with the vehicle and consistently seeking out the best value for your coverage needs. Regular policy reviews, leveraging available discounts, and maintaining a responsible driving record are your most effective tools. Remember that the cheapest policy is not always the best; prioritize adequate protection for your specific driving habits and the value of your Bronco.
Frequently Asked Questions About Bronco Insurance
Are Ford Broncos expensive to insure?
Ford Broncos generally tend to be more expensive to insure than many other SUVs due to their higher MSRP, specialized repair costs, potential for off-road use, and sometimes higher theft rates compared to more common family vehicles.
Does off-roading my Bronco affect my insurance?
While standard policies typically cover accidents on public roads, damage incurred during off-road activities might be subject to specific exclusions or require additional coverage. It's crucial to discuss your intended use with your insurer to understand policy limitations and ensure adequate protection.
Can modifications to my Bronco increase my insurance premiums?
Yes, significant modifications such as lift kits, larger tires, custom bumpers, or performance upgrades can increase your premiums. These changes can alter the vehicle's value, repair costs, and perceived risk. Always inform your insurer about modifications to ensure they are covered, as standard policies often exclude custom parts.
What is the best way to get a lower insurance rate for my Bronco?
The most effective strategies include comparing quotes from multiple insurance providers, increasing your deductibles if financially feasible, bundling your auto policy with other insurance types, maintaining a clean driving record, and inquiring about all applicable discounts.